Trepp is reporting that the overall CMBS special servicing rate continued to move higher in September, reaching 11.49%. The latest reading reflects a seven-basis-point increase from August and marks the highest level of special servicing activity since February 2013. September’s uptick followed a much sharper 33-basis-point rise in August, which had erased the decline recorded in July and underscored the persistence of stress across securitized commercial real estate loans.
The headline increase masked a divergent pattern by property type. Retail loans saw one of the more pronounced moves, with the special servicing rate climbing 24 basis points in September to 13.84%. Lodging loans also experienced a meaningful rise, with the rate increasing 21 basis points to 8.95%. Multifamily loans, while still carrying a lower special servicing rate than retail or office, also shifted higher during the month, rising 17 basis points to 8.54%.
Other sectors moved in the opposite direction, though from already elevated or relatively low baselines. Mixed-use loans recorded a decline of 30 basis points, bringing that sector’s special servicing rate down to 13.17%. Office loans, which remain among the most heavily watched categories in the CMBS universe, saw a modest five-basis-point decrease to 16.85%. Industrial loans continued to exhibit the lowest special servicing incidence among the major property types noted, with the rate edging down by four basis points to 1.23%.
New transfers into special servicing added to the pressure in September. According to Trepp, roughly $2.65 billion of CMBS loans moved into special servicing during the month, spread across 42 whole loans. Office properties represented the majority of this newly transferred volume, accounting for 57% of the total. This distribution reinforces the concentration of distress and refinancing challenges within the office segment of the CMBS market, even as other property types also registered higher special servicing activity.
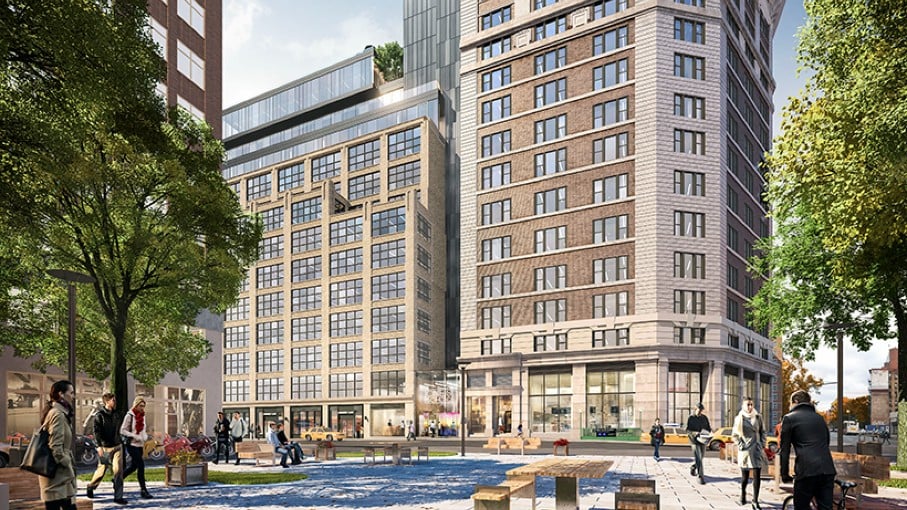
The largest individual loan to transfer to special servicing in September was the $512.8 million One SoHo Square loan. The collateral is an urban office property located in New York City. The loan was transferred for imminent balloon or maturity default, signaling that the borrower was facing challenges in repaying or refinancing the obligation at its scheduled maturity date. While the article does not provide further detail on the property, sponsorship, or loan structure, the size of the One SoHo Square loan makes it a notable component of the month’s transfer volume and an illustrative example of the refinancing pressures currently present in the CMBS office sector.
Taken together, the rising overall special servicing rate, the sector-level shifts, and the concentration of new transfers in office loans depict a CMBS landscape characterized by elevated distress levels relative to the last decade. The fact that the aggregate special servicing rate has reached its highest point since early 2013 highlights the extent to which maturing loans and property-level performance issues are now translating into active special servicing assignments across multiple commercial real estate property types.