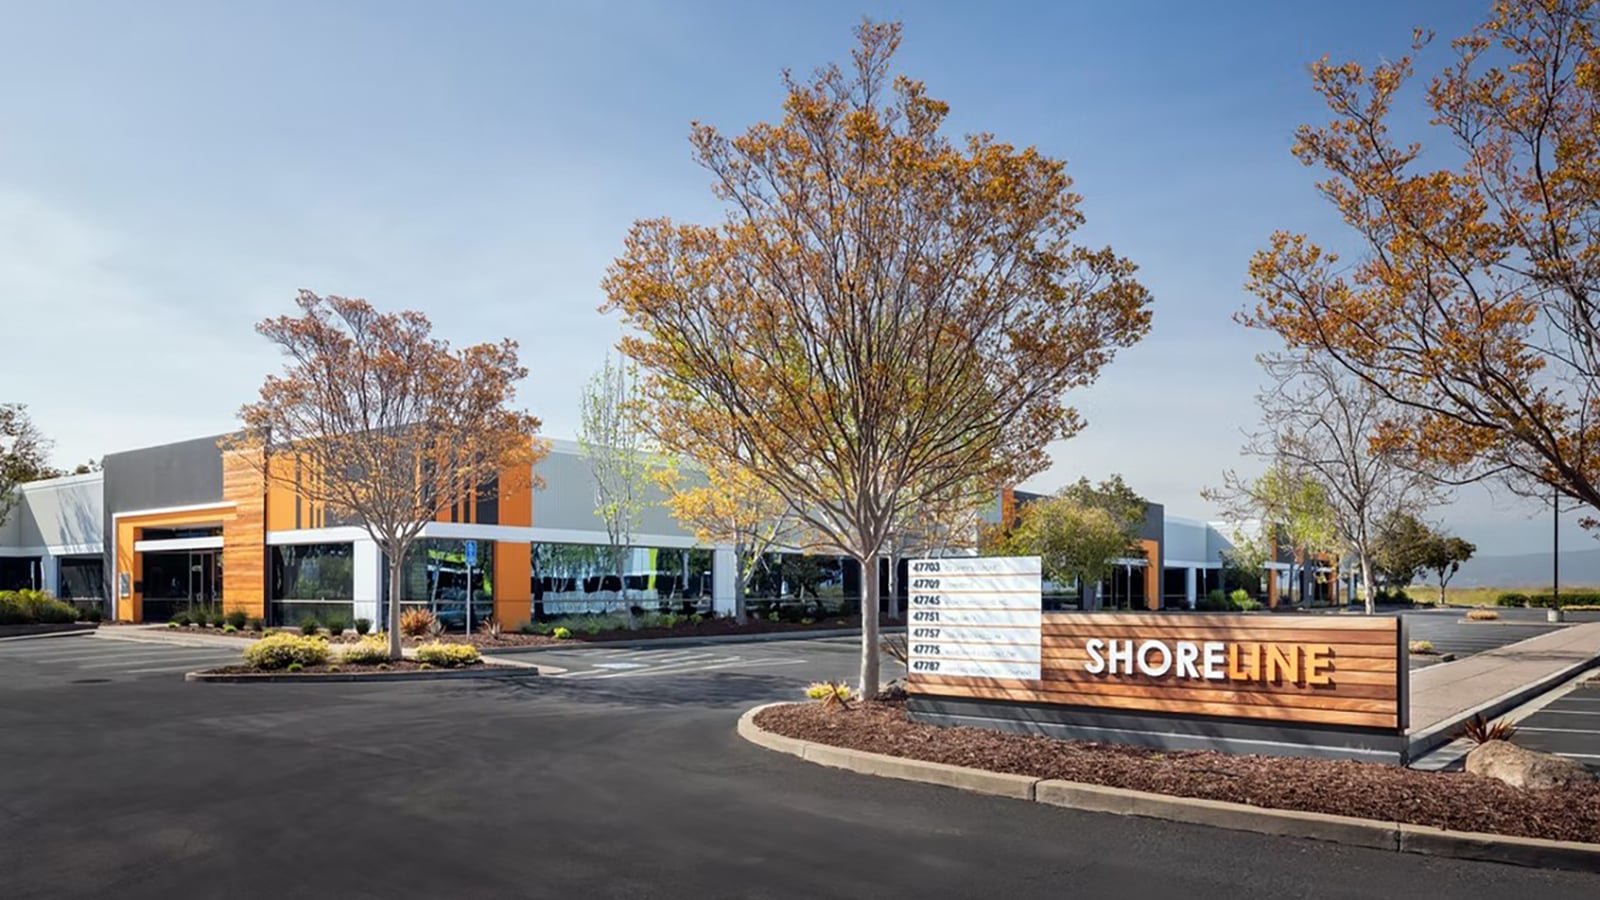
Mid-bay industrial is under pressure less from lack of demand than from how the sector itself defines the product. A new white paper from BKM Capital Partners argues that the traditional practice of sizing mid-bay space purely by building square footage misses how these assets actually function for tenants.
Industry definitions often rely on ranges such as 10,000 to 15,000 square feet with specified clear heights and loading configurations, or expand the cut-off to buildings as large as 100,000 square feet that serve local and regional operators. BKM instead emphasizes a combination of suite size, shallow-to-moderate building depth, loading, power, parking, access and infill location that supports active operating businesses rather than bulk storage.
Under that framework, a larger facility can contain multiple suites that operate as mid-bay, even if the overall building is categorized as large-bay. A 150,000-square-foot building that is typically labeled as a large-bay asset may, in practice, contain several 20,000- or 30,000-square-foot suites that function according to mid-bay characteristics. When industrial space is sorted only by total building size, those nuances and tenant needs are obscured.
This disconnect helps explain why mid-bay space remains tight despite healthy demand. New industrial construction has been robust, but much of it favors deep-footprint bulk warehouses. When a 15,000-square-foot suite is carved out of a deep building, the result can be an inefficient, narrow configuration with limited doors and shared truck courts. Shallower buildings, by contrast, can give similar-sized suites better frontage, dedicated loading and more functional parking.
BKM points to particularly limited availability for suites under 30,000 square feet within multi-tenant parks, even as new development skews toward larger-format facilities. Land and construction costs add further friction. The mid-bay format tends to work best in established infill locations near population centers, where sites are scarce and expensive. In multi-tenant parks, the need for more storefronts, restrooms, demising walls and separate electrical systems raises per-square-foot costs, while existing mid-bay assets can trade below replacement cost, making new projects harder to justify.
On the demand side, the tenant profile is evolving. Mid-bay users have long included regional distributors, light manufacturers, contractors and service businesses that have outgrown small-bay footprints but do not require big-box scale. Many of these firms are now adopting automation, advanced manufacturing and more sophisticated operating models, changing how they use space. Suites that once primarily needed clear height, dock doors and room for people and product are increasingly supporting automated equipment or production lines alongside warehousing and shipping.
As a result, prospective tenants may prioritize electrical capacity and the ability to add power over traditional metrics like clear height, while giving more weight to building appearance as part of their brand. Some operations also blur standard property categories. For instance, companies described as design, marketing or spa services may need space to fabricate exhibits, produce signage, manage printing or distribute products, combining warehouse or production functions with office requirements within a single suite.
Location remains central as well. Technology enables more output per worker and per square foot, but users still need access to specialized labor, customers, suppliers and transportation networks, reinforcing the appeal of infill industrial locations near population centers. The ongoing U.S. manufacturing buildout could intensify this need, as large campuses rely on networks of suppliers, equipment vendors, engineering firms, maintenance providers and logistics companies that often require flexible, well-located space rather than massive footprints.
BKM frames the conversation as clarifying a segment that never had a precise definition rather than renaming it. Industrial research generally groups properties by building size, a method that works reasonably well where single tenants occupy entire structures but less so in multi-tenant parks, where multiple mid-sized suites can reside within a single large building. When mid-bay space is folded into broad size categories, market data and underwriting can be distorted, affecting views on pricing, supply risk and tenant exposure.
The tenants that fall into this segment represent a significant share of small and midsize manufacturers, distributors and suppliers, many of them long-standing, often family-built businesses. BKM notes that this ties mid-bay performance closely to the health of that slice of the economy, and current indicators for those users are described as generally favorable.