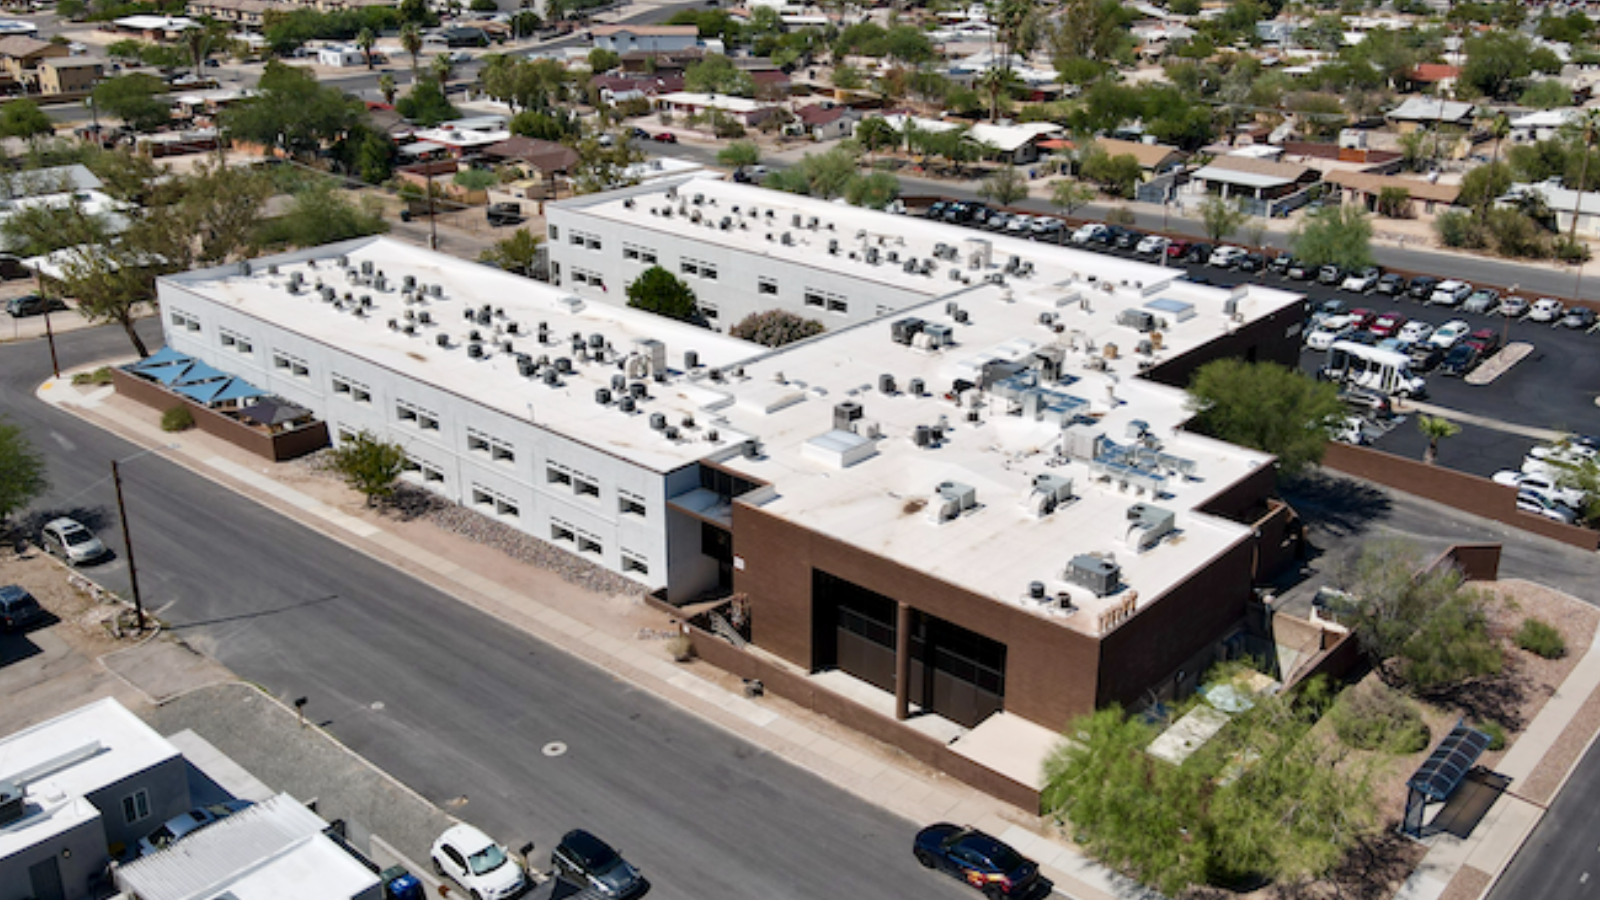
Debt distress and workouts continued across CMBS and balance-sheet lenders during the week of Oct. 8, 2026, spanning offices, malls and a Florida multifamily asset. In Washington, DC, an office building near Capital One Arena at 700 Sixth St. NW changed hands via a deed in lieu of foreclosure after its distressed loan was sold. An affiliate of a joint venture between Assembly Real Estate LLC and FitzWalter Capital Ltd. acquired the 305,759-square-foot property from an affiliate in the care of Affinius Capital LLC by purchasing the $140 million debt on the asset for $79.5 million.
In New York’s Financial District, Morningstar Credit reported the sale of 70 Broad St., a mixed-use office and residential building that has been in special servicing since March 2020 and vacant for years. The property sold for $9.4 million, well below the $14.1 million loan balance referenced in the WFCM 2015-NXS2 CMBS transaction and the $15.6 million appraised value recorded earlier in 2026.
Receivership and foreclosure continue to reshape challenged office assets. In Everett, WA, the former offices of Frontier Communications and The Everett Herald, a 15-acre site off Interstate 5 at 1800 41st St., moved through receivership proceedings after default on a $28 million CMBS loan and a March 2025 foreclosure by special servicer Rialto Capital. The site is now being evaluated for potential medium-to-high density residential redevelopment.
Retail distress remains acute for regional malls. In Pembroke Pines, the Pembroke Lakes Mall has been named in a $260 million foreclosure lawsuit filed Sept. 30 by Deutsche Bank on behalf of a CMBS trust. The 748,818-square-foot property at 11701 Pines Blvd. was appraised at $427 million when the CMBS loan was originated in 2013, but a Bloomberg CMBS data update from April showed a reduced appraised value of $112 million, leaving the loan significantly underwater and potentially headed for receivership.
In Greendale, WI, Morningstar Credit noted that a judge approved the receivership sale of Southridge Mall, backing a $100.9 million loan in the JPMBB 2013-C14 and JPMBB 2013-C12 CMBS transactions. The collateral is a 571,000-square-foot portion of a 1.2 million-square-foot regional mall that transferred to special servicing during the pandemic and remained unresolved until this court-approved sale.
Courts are also advancing lender remedies on mixed-use redevelopment sites. In Mission, KS, a Johnson County judge issued a final judgment allowing Metropolitan Commercial Bank to begin foreclosure on the long-stalled Mission Gateway project at the former Mission Mall site at Johnson Drive and Roe Avenue. Developer Aryeh Realty LLC defaulted on a $26 million loan tied to the project after months of litigation delays.
Not all distress is driven by valuation alone. In Allentown, PA, the $43.4 million St. Luke’s Office loan, securitized in the JPMCC 2017-JP7 and CSAIL 2017-C8 deals, transferred to special servicing after Intel, the second-largest tenant by space at 24% of NRA and 32.5% of underwritten base rent, vacated earlier in 2026. Despite historically strong net cash flow relative to underwriting, the loss of a major tenant triggered the servicing transfer.
In the multifamily sector, Morningstar Credit reported that The Wymore 360, a 200-unit property in Altamonte Springs, FL, moved to special servicing following several months of delinquency and payment default. The $33 million loan, representing 3.3% of the BMO 2024-5C8 CMBS transaction and referenced in CMBX.18, is secured by a property that has maintained occupancy above 90%, yet net cash flow has generally fallen below breakeven, and the exact cause of delinquency has not been disclosed.