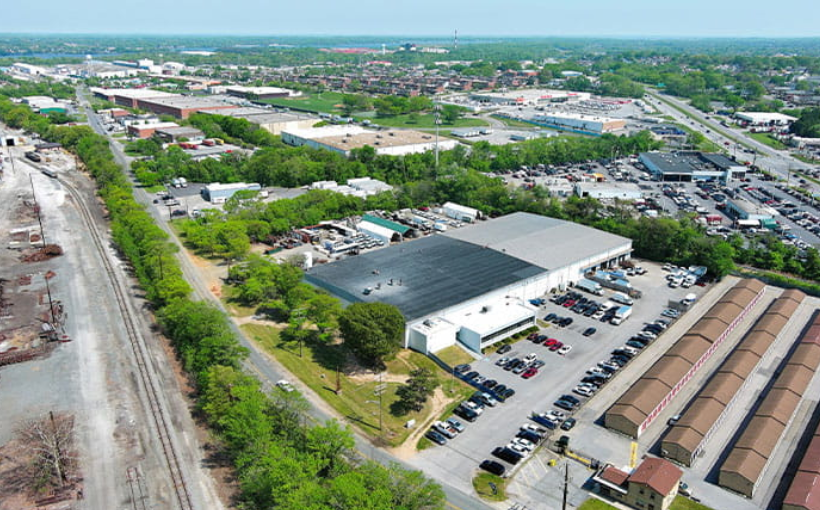
Data center expansion is generating new industrial demand across the Washington, D.C. region, with Northern Virginia accounting for a sizable share of recent activity. Since 2022, Northern Virginia has represented nearly 40 percent of U.S. data center permit activity, underscoring its role as a core hub for digital infrastructure and related industrial uses.
A recent report from Marcus & Millichap finds that this wave of data center-related activity has supported broader industrial fundamentals in the region. Over the past year, users absorbed more than 3.3 million square feet of newer industrial space, which helped work down what had been a notable supply overhang. The report indicates that the market has made measurable progress in digesting new deliveries that had previously weighed on vacancy and leasing performance.
Marcus & Millichap notes that Washington, D.C.’s industrial market has moved through a significant portion of its recent supply pipeline and that the pressure from those new deliveries is beginning to ease. According to Brian Hosey, senior managing director and market leader, Northern Virginia is driving much of this improvement. He points to the continued growth of the data center sector as a key source of incremental demand from contractors and other industrial users that support these facilities.
Vacancy trends reflect this momentum. As of June, industrial vacancy in the Washington, D.C. market declined to 7.6 percent. The report highlights that this made Washington, D.C. the only major Northeast market to register a year-over-year drop in industrial vacancy over the period reviewed. The decline suggests that tenants have been active enough to not only absorb new product but also tighten overall availability.
Pricing is moving in tandem with stronger occupancy. Average asking industrial rents in the Washington, D.C. region increased 5.1 percent year-over-year, according to the report. That rate of growth ranked as the fourth-largest annual rent increase among major U.S. industrial markets, signaling solid landlord pricing power in the face of sustained occupier demand. Together, the combination of rising rents, lower vacancy, and absorption of newer space points to a market where supply-side pressure is receding even as demand tied to the data center ecosystem continues to build.