The Trepp CMBS special servicing rate resumed its upward trajectory in August 2026, climbing 33 basis points to 11.42% and erasing the decline recorded in July. At this new level, the rate is now at its highest point since February 2013, underscoring mounting pressure across securitized commercial real estate loans.
Mixed-use assets saw the sharpest move during the month, driven largely by the transfer of a single $1.1-billion Hollywood studio-and-office loan to special servicing. That loan was the largest new transfer of the month and pushed the mixed-use special servicing rate up 154 basis points to 13.47%, according to Trepp.
Office loans also showed pronounced strain. The sector’s special servicing rate increased 32 basis points to 16.90%, with Trepp attributing the move to large central business district office loans being transferred to special servicing. Retail followed a similar path, rising 32 basis points to 13.60% as large mall and shopping center loans were added to the special servicing pipeline.
Lodging saw a more modest shift, with its special servicing rate ticking up 11 basis points to 8.74%. In contrast, industrial and multifamily were relative bright spots. Both sectors posted incremental improvements, with industrial special servicing falling seven basis points to 1.27% and multifamily declining three basis points to 8.37%.
Overall, transfers to special servicing in August totaled $3.16 billion across 32 whole loans, nearly double the transfer volume recorded in July. Trepp reported that transfers were concentrated in the office sector and that several of the largest loans moved to special servicing after exhausting their extension options.
Resolution activity lagged new distress. Loans that cured, were modified and returned from special servicing, or paid off during the month totaled approximately $500.7 million across 14 whole loans, materially smaller than the inflow of newly distressed loans. This imbalance highlights the growing overhang of troubled CMBS loans despite selective workouts and repayments.
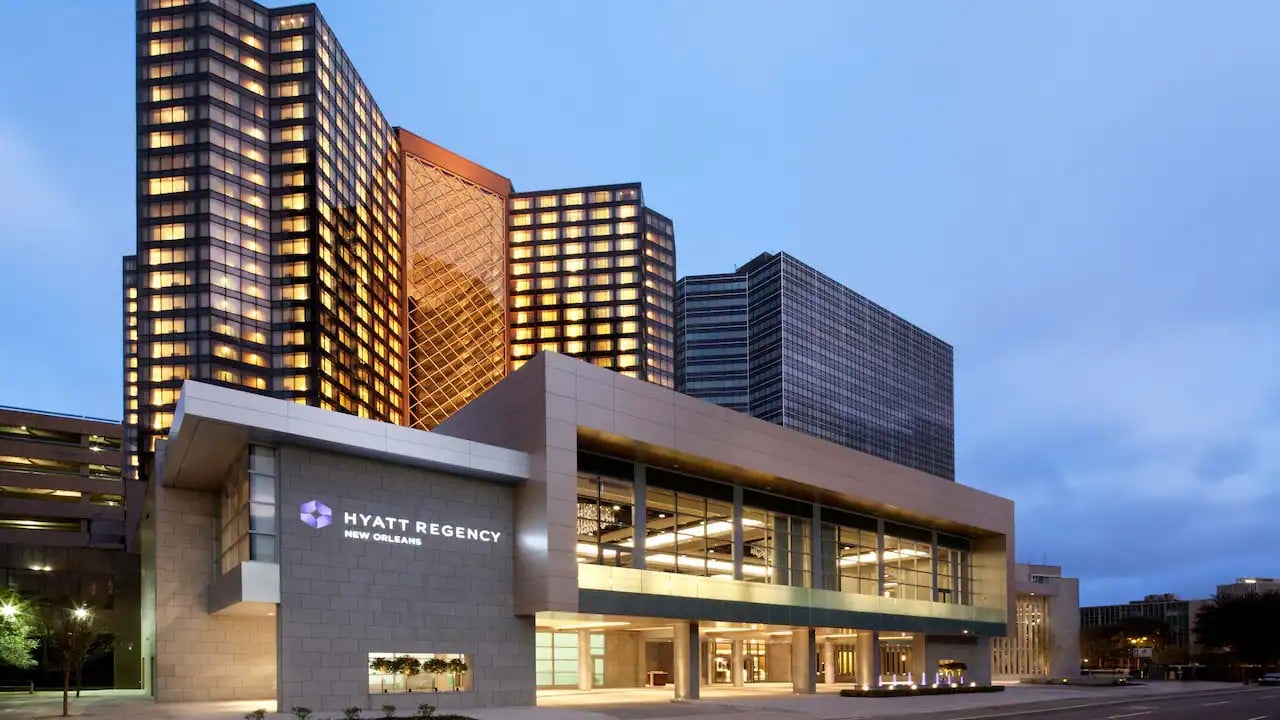
Among the notable assets entering special servicing was the CMBS loan secured by the Hyatt Regency New Orleans, which Trepp cited as one of the larger transfers during August. While property-specific terms were not disclosed, its inclusion alongside sizable office, retail, and mixed-use loans illustrates how stress is touching multiple segments and geographies within the CMBS universe.