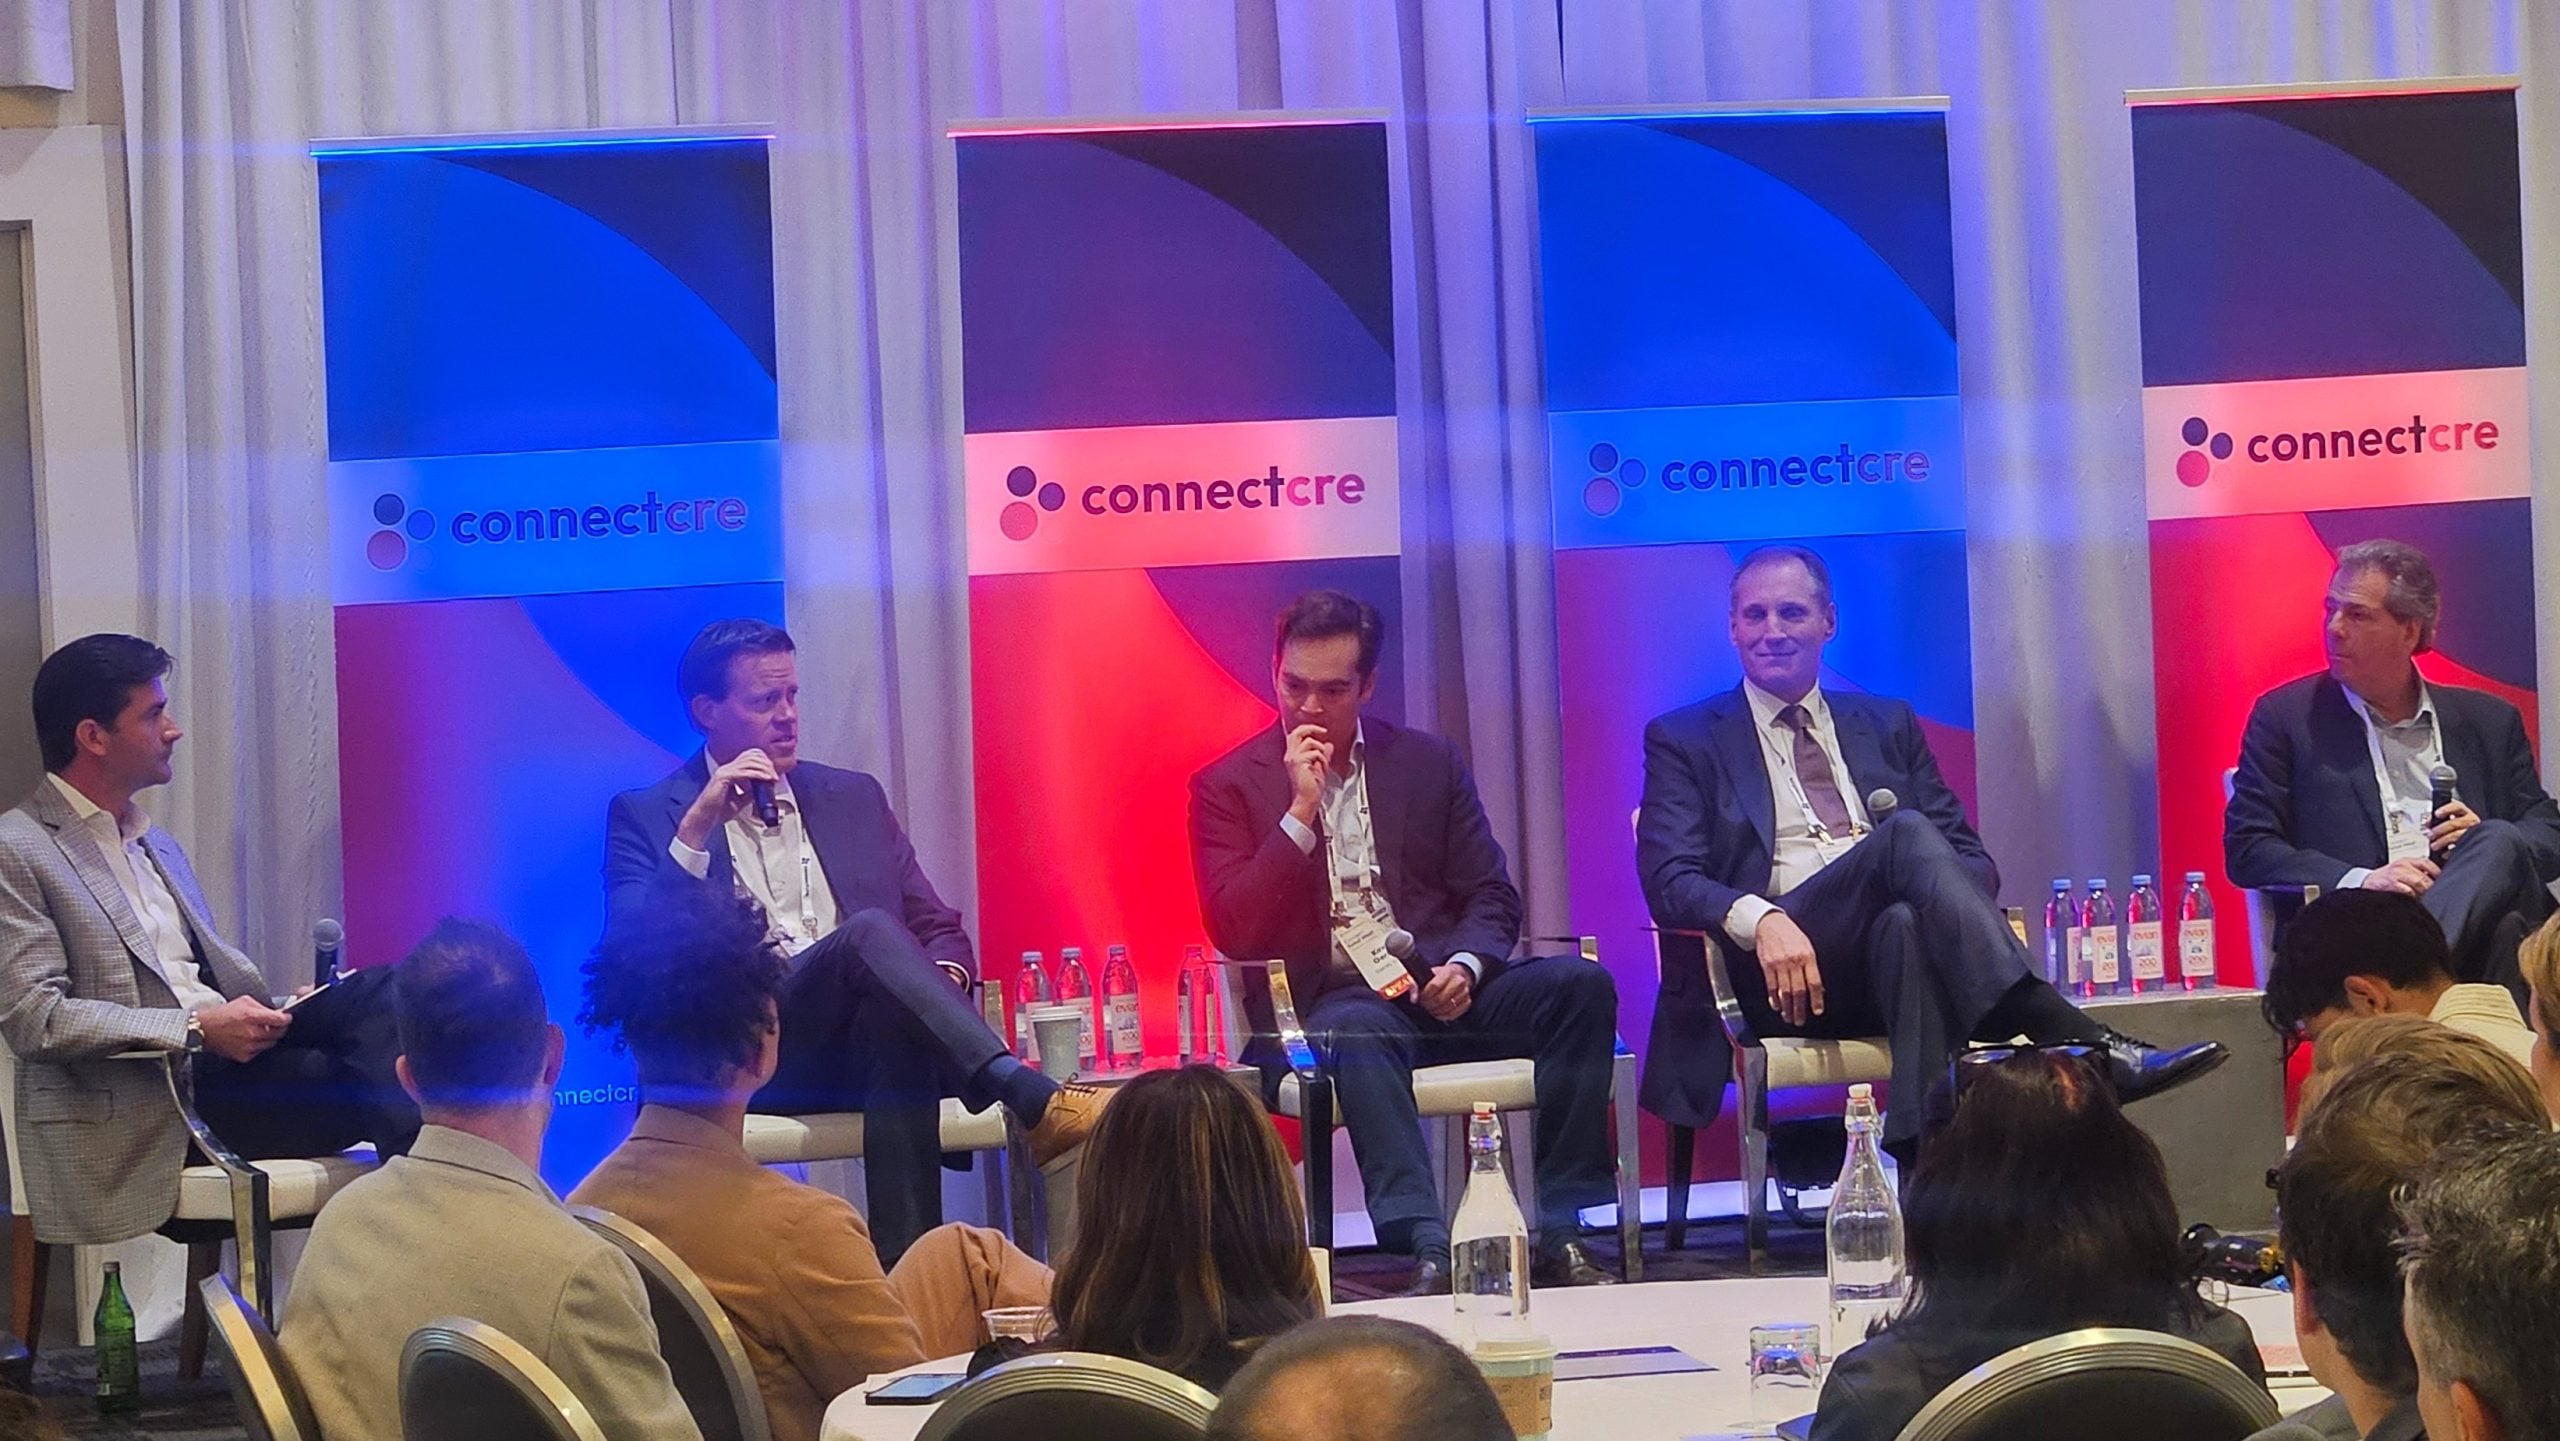
At the Connect Retail West 2026 conference in Los Angeles, owners, developers and restaurant executives described a retail landscape that has moved well beyond its “problem child” reputation. Landlords serving diverse, often underserved communities reported exceptionally strong demand for space, even as performance varies by center and leasing decisions have become more complex and highly site-specific.
Panelists said securing the right tenant now requires record tenant improvement outlays, higher common area and tax costs, and more intensive underwriting of concepts. Some owners are willing to spend heavily for the best operators in key locations, particularly where independent retailers can define a center’s identity. One owner noted that although mom-and-pop tenants may make up only a third of the roster, they can account for nearly all of a property’s character and local draw.
Restaurants were repeatedly cited as de facto anchors, but landlords and operators alike described the economics of new-build kitchens as increasingly difficult. Second-generation restaurant spaces are in high demand, and some landlords are taking a partnership-style approach, scouting chefs and investing significant time and capital into these tenants. Rising labor and insurance costs, particularly in California, are forcing owners to revisit traditional occupancy-cost formulas and get more comfortable with percentage rent structures.
Operator panelists stressed that rent is often a secondary consideration to fundamentals such as traffic patterns, co-tenancy and micro-location details like which side of the commute a shop sits on. Several said they would rather structure rents that keep strong tenants sustainable and capture upside via sales-based components than chase top-line rent that may not be viable given today’s higher product and labor costs.
Retailers are paying closer attention to day parts and dwell time, especially for concepts focused on breakfast and lunch or family-oriented uses. One operator described physically observing sites to understand real-world customer behavior, while another cited a 6,000-square-foot community venue that adds about two hours of dwell time per visit for families at a suburban center. Panelists urged landlords to track dwell time alongside sales per square foot and foot traffic.
Parking and site circulation remain critical, with mixed-use retail centers now serving curbside shoppers, fitness users, recreation leagues and restaurant guests across multiple day parts. Small physical frictions, such as stair access that discourages stroller traffic, were cited as lessons learned for future locations. Vacant big-box spaces were characterized as opportunities rather than liabilities, with some landlords quickly re-leasing former chains to value-focused retailers and others seeing potential in B and C malls where prior owners lacked capital or vision for repositioning.
On the capital side, one owner emphasized the importance of patient capital that underwrites assets on a seven- to 12-year hold horizon and prioritizes return on cost over internal rate of return. Panelists also called for greater flexibility around opening delays and rent commencement, given permitting, equipment and staffing issues, and noted that reputational considerations from the pandemic era have made both tenants and landlords more attuned to how they handle stress periods.
Looking ahead, owners showed less concern about headline holiday sales numbers than about how centers will perform once the seasonal spike passes, underscoring a focus on durable merchandising strategies over short-term statistics.